Kenya’s Banking Sector Generates KSh205.58 Billion in Taxes in 2025 as Financial Industry Strengthens Economy
Kenya's banking sector recorded a historic KSh205.58 billion in total tax contributions in 2025, representing a 5.53 per cent increase from the KSh194.81 billion reported in 2024. The figure, published in the Kenya Bankers Association's Total Tax Contribution Report 2025, represented approximately 8 per cent of total government revenue and 22.15 per cent of corporate tax receipts. The contribution consisted of KSh98.36 billion in taxes borne directly by participating institutions and KSh107.22 billion collected on behalf of the government. Increased withholding tax collections, employment-related taxes and excise duty helped shape the overall results.
Kenya’s banking sector recorded an impressive KSh205.58 billion in tax payments in 2025, highlighting the financial industry’s significant contribution to government revenue and the wider economy. The reported figure underscores the importance of banks as major corporate taxpayers, employers, lenders and facilitators of business activities across the country.
The banking industry plays a central role in Kenya’s economic development by supporting businesses, providing loans to households and enterprises, facilitating domestic and international payments, and helping the government collect revenue. The substantial tax contribution also draws attention to the profitability of financial institutions, the expansion of digital banking services and the growing importance of financial services in the country’s economic structure.However, the figure should be understood in the context of the specific taxes included in the reported total. Corporate income tax, taxes withheld on certain payments, and other tax obligations may contribute differently to the overall amount. The precise breakdown is necessary to establish how much was paid directly by banks from their profits and how much was collected or remitted on behalf of other taxpayers.
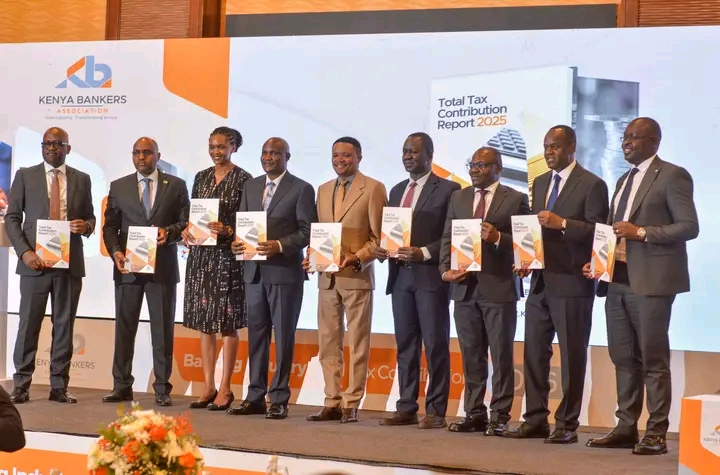
The record was highlighted in the seventh edition of the Total Tax Contribution Report by the Kenya Bankers Association (KBA), prepared in collaboration with PwC Kenya. The report, released on October 22, 2026, shows that the participating banks and microfinance institutions contributed KSh205.58 billion to the government in 2025, representing an increase of 5.53 per cent from KSh194.81 billion in 2024.KSh98.36 billion
Taxes paid directly by the participating financial institutions.
Taxes collected on behalf of government
KSh107.22 billion
Taxes deducted, collected or withheld and subsequently remitted.
Total tax contribution KSh205.58 billion
These figures show that the amount collected on behalf of the government exceeded the taxes paid directly by the institutions themselves. This was a notable development in the sector's tax history and demonstrates the important role banks play in administering the country's tax system. Banking sector accounts for 8 per cent of government revenue
The participating institutions accounted for approximately 8 per cent of total government revenue in 2025. They also contributed 22.15 per cent of the corporate income tax collected by the government, meaning that more than one-fifth of the country's corporate tax receipts was associated with this group of financial institutions.
This contribution is particularly important for a government that needs reliable revenue to finance public services and development projects. Tax revenue helps fund education, healthcare, roads, electricity connections, water projects, security services and other national priorities.Corporate income tax remains a major contributor
Corporate income tax is the tax charged on the taxable profits of companies. It is one of the principal ways through which profitable banks contribute directly to public finances.
The 2025 report indicates that corporate income tax payments associated with the participating institutions rose by 2.06 per cent to KSh70.84 billion, compared with KSh69.41 billion in 2024. Meanwhile, the Central Bank of Kenya's annual report recorded banking-sector profit before tax of approximately KSh306 billion in 2025, up from KSh260.3 billion in 2024. Withholding tax drives the increase in tax collections
Withholding tax emerged as one of the most important factors behind the increase in the banking sector's overall tax contribution in 2025.
According to the published report, withholding tax collections rose by approximately 29.4 per cent to KSh43.95 billion, up from KSh33.97 billion in 2024. The increase made withholding tax the second-largest component of the sector's total tax contribution, overtaking employment-related taxes.
Withholding tax is generally deducted at source from specified payments and remitted to the tax authority. Depending on the payment and the applicable law, it may apply to interest, professional fees, royalties and other categories of income.Excise duty and taxes associated with financial services
Excise duty is another component of the sector's tax contribution. In financial services, applicable excise duty can be charged on specified fees and commissions, depending on the law in force.
The 2025 report showed that excise duty collections increased by 5.46 per cent to KSh23.90 billion from KSh22.66 billion in 2024. The report linked the growth partly to a recovery in lending activity, which can increase the volume of taxable financial transactions and service fees. The KSh205.58 billion contribution demonstrates the importance of the financial services industry to Kenya's formal economy.
Banks provide the infrastructure that enables households, businesses and public institutions to move money securely. They help businesses manage payments, finance investment, pay workers and engage in domestic and international trade.
When businesses access credit and invest in new operations, they may expand production, employ additional workers and generate taxable income. Banks can therefore support government revenue indirectly by helping other sectors of the economy grow.Rising tax compliance costs concern banks
Although the increase in tax contributions represents a major revenue achievement for the government, participating institutions have raised concerns about the cost and complexity of complying with tax requirements.
The report found that the average annual tax compliance cost per participating institution increased by approximately 62 per cent, rising from KSh19.10 million in 2024 to KSh30.99 million in 2025. Institutions also spent an average of about 103 business hours each month on tax compliance and made approximately 45 tax payments monthly. Government urged to balance taxation with economic growth
The record contribution has renewed discussions about how Kenya can maintain strong revenue collection while supporting business expansion, employment and household welfare.
National Treasury Cabinet Secretary John Mbadi has acknowledged the importance of balancing tax policy with the financial pressures facing households. Discussions around PAYE reforms and improvements to tax administration reflect the broader challenge of financing public services while ensuring that taxation remains manageable for workers and businesses.The banking sector's tax contribution is likely to remain an important indicator of Kenya's revenue performance. Future figures will depend on several factors, including bank profitability, customer deposits, lending activity, changes in tax legislation, employment levels and the volume of financial transactions.
The government will also need to consider whether the growth in tax collections is accompanied by improvements in public services and responsible use of public funds. Taxpayers ultimately expect government revenue to support development, improve essential services and create an environment in which businesses and households can prosper.
For customers, the relationship between taxation and banking costs will remain important. Changes in the cost of compliance, excise duty and other levies can influence how financial institutions price certain services. However, the extent to which any particular tax change affects customer charges depends on the institution's costs, competitive pressures and the applicable legal framework.